Welcome. Before You Begin:
Understanding your ownership, control, or beneficial interest in a foreign trust or offshore partnership—and the associated U.S. tax and reporting obligations—requires careful attention. We are here to help.
As you evaluate the information below, you remain in complete control of your timeline and decisions.
If this material confirms a risk, raises a concern, or if you require immediate clarification, there are multiple ways to easily connect with us for free insight to learn more. You do not need to interrupt your reading or navigate away from this page to secure that guidance:
- Direct Phone Access: Our phone number is anchored in the upper right menu.
- Continuous Chat Support: Actively present on your screen for immediate connection.
- Secure Inquiry: The “Contact Us” menu option above is a direct, private way to connect with us or request a free consultation.
This firm provides a substantive, confidential consultation at no cost. You are invited and encouraged to read the material ahead to orient yourself. When you’re ready to ask questions, or discuss the specific facts of your situation, we invite you to reach out.
I Have an Interest in a Foreign Trust, but I'm Not Sure What the IRS Considers Me to Be
You have a connection to a foreign trust, but the documents, ownership arrangements, and your actual responsibilities may not tell the same story.
- You inherited or acquired an interest in a trust established outside the United States.
- You are uncertain whether you are considered an owner, grantor, trustee, or beneficiary.
- The trust was established under foreign laws you do not fully understand.
- Someone else manages the trust, but you may retain certain rights or authority.
- You are unsure whether the trust has been properly identified or reported for U.S. tax purposes.
Learn More →
I'm a Beneficiary of a Foreign Trust, but I Don't Know What I Must Report
You have been named as a beneficiary of a foreign trust, and you are uncertain whether your rights or distributions create U.S. tax and reporting obligations.
- You have been told you are a beneficiary but have received little information about the trust.
- You may be entitled to distributions even though you have not received any money.
- You recently received money or property from a foreign trust.
- You do not understand how the trustee calculates or characterizes distributions.
- You are uncertain whether your interest should have appeared on previous U.S. tax returns.
Learn More →
I Established or Transferred Assets into a Foreign Trust, and I'm Concerned About the Tax Consequences
You created, funded, or contributed property to a foreign trust and now have questions about the U.S. tax consequences of those decisions.
- You established a foreign trust for family, estate planning, business, or asset protection purposes.
- You transferred cash, investments, real estate, or other property into the trust.
- You were advised that the trust would provide tax or asset protection advantages.
- Family members or other U.S. persons may benefit from the trust.
- You are uncertain whether the original transfers or subsequent trust activity were properly reported.
Learn More →
I've Received Money, Borrowed Funds, or Used Property Belonging to a Foreign Trust
You have received a financial benefit from a foreign trust, but you are unsure how the IRS may view the transaction or whether it was properly documented.
- You received money from the trust without a clear explanation of its tax treatment.
- You borrowed funds from a foreign trust or have an outstanding trust-related loan.
- You or a family member have used real estate or other property owned by the trust.
- Payments or transfers were handled informally between family members and trustees.
- You are uncertain how these transactions were reflected in the trust's records or your tax filings.
Learn More →
My Foreign Trustee Hasn't Provided the Records I Need to Understand or Report My Interest
You are expected to account for your connection to a foreign trust, but the people responsible for its administration have not provided the information you need.
- The trustee is located overseas and communication has been difficult.
- You have not received complete financial statements or trust documents.
- You are uncertain how much income the trust earned or what assets it holds.
- Your accountant has requested information that the trustee has not supplied.
- U.S. filing deadlines are approaching, or previous returns were prepared using incomplete information.
Learn More →
I Didn't Report My Foreign Trust in Previous Years, and I'm Worried About IRS Penalties
You recently discovered that your foreign trust may have created U.S. reporting obligations that were missed or handled incorrectly in earlier years.
- You have held an interest in a foreign trust for years without filing trust-related disclosures.
- You relied on a foreign adviser who did not discuss U.S. reporting requirements.
- You assumed no reporting was necessary because you received little or no income.
- Your accountant recently identified missing forms or inconsistencies in previous returns.
- You are concerned about penalties, an IRS inquiry, or the consequences of correcting past filings.
Learn More →
I Own an Interest in an Offshore Partnership, but I Don't Understand My U.S. Tax and Reporting Responsibilities
You own or have acquired an interest in a foreign partnership and are uncertain how your ownership, participation, or control affects your U.S. tax obligations.
- You invested in or became a partner in a business organized outside the United States.
- You inherited or acquired a partnership interest through a family or business arrangement.
- You own a minority interest but are unsure whether your ownership percentage matters.
- You participate in management or have authority over partnership decisions.
- You do not know whether the partnership's income or your ownership interest was properly reflected in your U.S. filings.
Learn More →
My Offshore Partnership Has Financial Activity or Missing Records That May Affect My U.S. Tax Returns
Your foreign partnership has income, transactions, or reporting issues that you do not fully understand, and you are concerned about your personal U.S. tax responsibilities.
- The partnership operates overseas and provides financial information under foreign accounting rules.
- You received distributions or payments that were not clearly identified.
- You contributed capital, transferred property, or changed your ownership interest.
- Your foreign partners or accountants have not provided complete financial records.
- You recently discovered that prior U.S. tax returns may not have reflected the partnership's activity correctly.
Learn More →
I Have an Interest in a Foreign Trust, but I'm Not Sure What the IRS Considers Me to Be
Foreign Trust Classification • Ownership and Control • Beneficial Interests • U.S. Tax Responsibilities • Understanding Your Position
A foreign trust may have been established by a parent, grandparent, family adviser, or business associate long before you became involved. You may have inherited an interest, accepted responsibilities as a trustee, or discovered that you possess certain rights over trust assets. Yet the terminology used in the foreign trust documents may not determine how the United States treats your relationship to the trust.
The central question is not simply what the foreign documents call you. It is how U.S. tax law classifies the trust and your actual relationship to it.
Foreign Trust Classification Is More Complicated Than Its Name or Location
A trust established outside the United States is not necessarily classified as foreign for U.S. federal tax purposes. The IRS applies specific tests concerning court supervision and control over substantial trust decisions. The location of the assets, residence of the trustee, governing documents, and decision-making arrangements may be relevant, but no single label resolves every question.
This distinction matters because a trust's U.S. classification can affect its income tax treatment, reporting obligations, and the responsibilities of people connected to it.
Ownership, Control, and Beneficial Interests Are Different Questions
You may have authority to direct investments, approve distributions, replace trustees, or receive trust property without understanding how those rights affect your U.S. tax position.
A person identified as a beneficiary under foreign law is not necessarily treated as the owner of trust income under U.S. tax law. Conversely, someone who transferred assets to a trust may retain U.S. tax responsibilities even after legal title has passed to the trustee.
The distinction between a foreign grantor trust and a foreign nongrantor trust can be particularly consequential. Determining the appropriate treatment requires examining the trust documents, the parties involved, the source of its assets, and the rights actually retained or exercised.
Why an Accurate Understanding Matters
An incorrect classification can affect how income is reported, which information returns may be required, and whether earlier filings accurately reflected the arrangement.
Janathan Allen and the coordinated legal, tax, and accounting professionals at Allen Barron can examine the underlying documents and financial relationships together, rather than treating the trust designation as a complete answer.
The Most Important Step You Can Take Right Now.
It is important to understand where you are in this moment, the information you might be missing, the best actions and communications to undertake (and those to avoid), and the most productive and effective steps you can take to protect your interests and accomplish your objectives.
We invite you to a free, substantive consultation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling 866-631-3470.
Many foreign trust classification and ownership issues are influenced not only by what has already happened, but by what happens next. An early conversation with our firm can help you better understand your position, your risks, your opportunities, and the actions that may improve the likelihood of achieving a successful outcome.
I'm a Beneficiary of a Foreign Trust, but I Don't Know What I Must Report
Beneficiary Rights • Grantor vs. Nongrantor Trusts • Distribution Tax Treatment • Trustee Statements • U.S. Reporting Obligations
Being named as the beneficiary of a foreign trust does not necessarily mean you control its assets, receive regular income, or even understand how the trust operates. The trustee may be overseas, distributions may be discretionary, and the trust may have been established under a legal system unfamiliar to you.
You may have received a distribution, been promised future benefits, or learned of your interest only recently.
Your U.S. tax responsibilities depend on the nature of your interest, the trust's classification, and the transactions that have actually occurred—not simply the fact that you are called a beneficiary.
A Beneficial Interest Is Not the Same as Receiving Taxable Income
Foreign trust beneficiaries may have different reporting and tax consequences depending on whether the trust is treated as a grantor or nongrantor trust and whether distributions have occurred.
For example, a distribution from a foreign nongrantor trust may include amounts treated differently for U.S. income tax purposes. In certain circumstances, distributions of accumulated income can create additional tax and interest consequences.
By contrast, merely being named as a possible future beneficiary does not automatically establish that you have received taxable income or must file every foreign trust information return.
What the Trustee Reports Can Affect Your Tax Position
Foreign trustees may provide beneficiary statements intended to help U.S. recipients determine the tax treatment of distributions. The availability, completeness, and accuracy of these statements can materially affect the analysis.
Problems arise when the beneficiary receives money without supporting records, the trustee uses foreign tax terminology that does not translate directly into U.S. reporting categories, or distributions from different years are not adequately documented.
Understanding Your Actual Position
A careful review should distinguish your rights under the trust from benefits already received, identify the character and timing of distributions, and determine whether applicable U.S. disclosures have been satisfied.
Allen Barron's integrated legal and tax capabilities are particularly relevant when the trust's legal provisions and financial records must be interpreted together.
The Most Important Step You Can Take Right Now.
It is important to understand where you are in this moment, the information you might be missing, the best actions and communications to undertake (and those to avoid), and the most productive and effective steps you can take to protect your interests and accomplish your objectives.
We invite you to a free, substantive consultation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling 866-631-3470.
Many foreign trust beneficiary and distribution issues are influenced not only by what has already happened, but by what happens next. An early conversation with our firm can help you better understand your position, your risks, your opportunities, and the actions that may improve the likelihood of achieving a successful outcome.
I Established or Transferred Assets into a Foreign Trust, and I'm Concerned About the Tax Consequences
Foreign Trust Formation • Tax Consequences of Asset Transfers • Continuing Ownership Rules • Forms 3520 and 3520-A • Future Contributions and Changes
Foreign trusts may serve legitimate family, succession, estate planning, and asset management purposes. You may have established one following advice from foreign counsel, transferred inherited property, or placed assets into a trust to benefit family members living in different countries.
The difficulty arises when the legal purpose of the arrangement is understood, but its U.S. tax consequences are not.
Transferring property to a foreign trust does not necessarily end your U.S. tax responsibilities—and the consequences may begin with the transfer itself.
The Original Transfer Can Have Continuing Consequences
When a U.S. person transfers property to a foreign trust, the tax consequences depend on the nature of the transfer, the trust's classification, the identity of its beneficiaries, and the applicable statutory rules.
Certain transfers can trigger recognition of gain. Other arrangements may result in the U.S. transferor being treated as the owner of trust assets or income for federal income tax purposes, particularly where the applicable foreign trust rules concerning U.S. beneficiaries are satisfied.
These questions cannot be resolved merely by confirming that the trust was validly established under foreign law.
Reporting Responsibilities May Continue After Funding
Form 3520 may be required for certain transfers to foreign trusts and other reportable transactions. Form 3520-A may apply to foreign trusts with U.S. owners under the relevant tax rules.
Depending on the assets and accounts involved, other U.S. international information reporting requirements may also arise.
The filing responsibilities, deadlines, and consequences of incomplete reporting differ. It is important to determine which requirements actually apply rather than assuming every offshore arrangement is subject to the same forms.
Examine the Structure Before Making Additional Changes
Additional contributions, changes in beneficiaries, amendments to trust documents, and changes in control may affect the analysis.
Janathan Allen and Allen Barron's coordinated legal, tax, and accounting professionals can evaluate the original purpose, legal structure, funding history, and reporting position together, including the implications of contemplated future transactions.
The Most Important Step You Can Take Right Now.
It is important to understand where you are in this moment, the information you might be missing, the best actions and communications to undertake (and those to avoid), and the most productive and effective steps you can take to protect your interests and accomplish your objectives.
We invite you to a free, substantive consultation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling 866-631-3470.
Many foreign trust establishment and asset transfer issues are influenced not only by what has already happened, but by what happens next. An early conversation with our firm can help you better understand your position, your risks, your opportunities, and the actions that may improve the likelihood of achieving a successful outcome.
I've Received Money, Borrowed Funds, or Used Property Belonging to a Foreign Trust
Trust Distributions • Loans and Repayment Requirements • Use of Trust Property • Transaction Documentation • U.S. Tax Consequences
You may have received money from a foreign family trust, borrowed funds for a business or home purchase, or used real estate owned by the trust. Within the family, these arrangements may have seemed informal or entirely routine.
U.S. tax law, however, can distinguish between a genuine loan, a trust distribution, compensation, and other forms of financial benefit.
What the parties intended, how the transaction was documented, and what actually occurred can all matter when determining its U.S. tax consequences.
Not Every Payment or Benefit Is Treated the Same Way
A distribution from a foreign trust may have different consequences depending on the trust's tax classification, the beneficiary's status, and the character of the amounts distributed.
Loans from foreign trusts to U.S. persons may also be subject to special rules. A purported loan that does not satisfy applicable requirements can potentially be treated as a distribution rather than as ordinary borrowed funds.
Similarly, uncompensated use of certain trust property by a U.S. person can have consequences under the foreign trust rules.
Informal Family Arrangements Can Create Documentation Problems
A trustee may have transferred money without identifying whether it was a loan, gift, distribution, or reimbursement. A family member may have occupied trust-owned property without a written agreement. Repayment terms may have been discussed but never recorded.
The absence of clear records can make it difficult to establish the transaction's actual nature and report it accurately.
The Transaction History Matters
The analysis may require reviewing trust agreements, payment records, loan documents, property use, trustee communications, and prior tax filings.
Allen Barron's integrated approach allows the legal characterization of a transaction to be considered alongside the accounting records and resulting U.S. tax obligations.
The Most Important Step You Can Take Right Now.
It is important to understand where you are in this moment, the information you might be missing, the best actions and communications to undertake (and those to avoid), and the most productive and effective steps you can take to protect your interests and accomplish your objectives.
We invite you to a free, substantive consultation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling 866-631-3470.
Many foreign trust distribution, loan, and property-use issues are influenced not only by what has already happened, but by what happens next. An early conversation with our firm can help you better understand your position, your risks, your opportunities, and the actions that may improve the likelihood of achieving a successful outcome.
My Foreign Trustee Hasn't Provided the Records I Need to Understand or Report My Interest
Missing Trust Documents • Foreign Trustee Cooperation • U.S. Filing Responsibilities • Potential Reporting Penalties • Legal and Accounting Coordination
Your foreign trustee may control the documents and financial information needed to understand the trust, while your U.S. accountant is asking questions you cannot answer. The trustee may be unfamiliar with American reporting requirements, may provide incomplete statements, or may simply be difficult to reach.
Meanwhile, U.S. filing deadlines and reporting responsibilities may continue regardless of how quickly the trustee responds.
The challenge is determining what information is missing, why it matters, and which U.S. obligations remain your responsibility despite the trustee's lack of cooperation.
Foreign Trustees and U.S. Taxpayers May Have Different Reporting Expectations
A trustee operating under foreign law may prepare records sufficient for local administration but insufficient to establish the trust's U.S. tax classification, income, distributions, or reportable transactions.
The documents needed may include the trust agreement and amendments, financial statements, details of contributions and distributions, information about beneficiaries, and records of relevant financial accounts.
The appropriate requests depend on the taxpayer's relationship to the trust and the reporting obligations under examination.
Missing Information Does Not Necessarily Eliminate Filing Responsibilities
Certain foreign trust information returns carry significant penalties for failure to report required information. The availability of reasonable-cause relief depends on the applicable law and the specific facts.
A trustee's failure to cooperate may be relevant to understanding why information was unavailable, but it should not automatically be assumed to excuse every incomplete or missing filing.
Legal and Accounting Coordination Can Be Essential
Obtaining documents is only part of the problem. The information must also be evaluated under the applicable U.S. tax rules.
Janathan Allen and the Allen Barron team can examine the taxpayer's legal rights to information, the reporting requirements at issue, the available records, and the potential consequences of missing information.
The Most Important Step You Can Take Right Now.
It is important to understand where you are in this moment, the information you might be missing, the best actions and communications to undertake (and those to avoid), and the most productive and effective steps you can take to protect your interests and accomplish your objectives.
We invite you to a free, substantive consultation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling 866-631-3470.
Many foreign trust documentation and reporting issues are influenced not only by what has already happened, but by what happens next. An early conversation with our firm can help you better understand your position, your risks, your opportunities, and the actions that may improve the likelihood of achieving a successful outcome.
I Didn't Report My Foreign Trust in Previous Years, and I'm Worried About IRS Penalties
Missing Foreign Trust Filings • Substantial IRS Penalties • Reasons for Noncompliance • Available Correction Procedures • Protecting Your Position
Perhaps you believed that a foreign trust did not require U.S. reporting because its assets remained overseas, you received no distributions, or a foreign adviser assured you that everything had been handled properly.
Now an accountant, financial institution, or IRS notice has raised questions about earlier years.
The immediate concern is not simply whether a form was missed. It is understanding what should have been reported, how the omission occurred, and what consequences may follow from the next steps you take.
Foreign Trust Reporting Penalties Can Be Substantial
Failure to comply with applicable Form 3520 or Form 3520-A requirements can result in significant penalties. Depending on the particular reporting obligation, penalties may be calculated by reference to the value of trust property, reportable transfers, or distributions, subject to the governing statutory provisions.
These information-reporting penalties can arise independently of whether the taxpayer owes additional income tax.
Other foreign asset or account reporting requirements may also be relevant, but they must be evaluated separately.
The Circumstances Behind the Omission Matter
There is a meaningful difference between a taxpayer who misunderstood a complicated filing obligation, one who relied on incomplete professional advice, and one who deliberately concealed foreign assets or income.
The facts may affect the availability of particular compliance procedures, penalty relief, and the potential seriousness of the matter.
It is also important to distinguish an IRS examination already underway from a taxpayer's discovery of an error before the IRS has made contact. Available options can differ.
Correcting the Past Requires More Than Filing Missing Forms
Prior-year trust records, distributions, income reporting, communications with advisers, and earlier returns may all need review.
Submitting amended returns or delinquent information forms without first understanding the complete history can create avoidable complications.
Janathan Allen's legal and tax experience, supported by Allen Barron's coordinated accounting capabilities, can help establish the facts and evaluate the appropriate response before potentially consequential communications or filings are made.
The Most Important Step You Can Take Right Now.
It is important to understand where you are in this moment, the information you might be missing, the best actions and communications to undertake (and those to avoid), and the most productive and effective steps you can take to protect your interests and accomplish your objectives.
We invite you to a free, substantive consultation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling 866-631-3470.
Many prior-year foreign trust reporting and penalty issues are influenced not only by what has already happened, but by what happens next. An early conversation with our firm can help you better understand your position, your risks, your opportunities, and the actions that may improve the likelihood of achieving a successful outcome.
I Own an Interest in an Offshore Partnership, but I Don't Understand My U.S. Tax and Reporting Responsibilities
U.S. Entity Classification • Partnership Ownership and Control • Form 8865 Reporting • Income Without Distributions • Your U.S. Tax Obligations
You may own part of a business operating overseas, participate in a family partnership established under foreign law, or hold an investment interest managed by partners outside the United States.
Your ownership may be substantial or relatively small. You may actively participate in management or have little involvement in daily operations.
The important questions include how the entity is classified for U.S. tax purposes, what your actual ownership and participation mean, and which U.S. tax and reporting requirements apply to your particular interest.
A Foreign Business Entity Is Not Automatically Treated as a Partnership by the IRS
An entity described as a partnership under foreign law may be classified differently for U.S. federal tax purposes.
The analysis may involve the entity's legal characteristics, applicable U.S. classification rules, and any relevant elections.
This determination matters because the treatment of income, losses, distributions, and ownership reporting can differ significantly depending on whether the entity is classified as a partnership, corporation, or another type of entity.
Ownership Percentage and Control Can Affect Reporting Obligations
U.S. persons with certain interests in foreign partnerships may have reporting responsibilities under Form 8865.
The applicable filing category can depend on ownership, control, contributions, acquisitions, dispositions, and other specified circumstances.
A minority interest does not automatically eliminate all potential reporting requirements. Similarly, participation in management is not interchangeable with the ownership tests established under the applicable rules.
Income Reporting and Information Reporting Are Separate Questions
A U.S. partner may have to account for a share of partnership income even when the partnership does not distribute an equivalent amount of cash.
The precise treatment depends on the entity's classification, the taxpayer's relationship to it, and the applicable tax rules.
Janathan Allen and Allen Barron's coordinated legal, tax, and accounting professionals can examine the foreign entity's legal structure and financial activity alongside the U.S. taxpayer's ownership and reporting responsibilities.
The Most Important Step You Can Take Right Now.
It is important to understand where you are in this moment, the information you might be missing, the best actions and communications to undertake (and those to avoid), and the most productive and effective steps you can take to protect your interests and accomplish your objectives.
We invite you to a free, substantive consultation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling 866-631-3470.
Many offshore partnership ownership and reporting issues are influenced not only by what has already happened, but by what happens next. An early conversation with our firm can help you better understand your position, your risks, your opportunities, and the actions that may improve the likelihood of achieving a successful outcome.
My Offshore Partnership Has Financial Activity or Missing Records That May Affect My U.S. Tax Returns
Foreign Partnership Financial Records • U.S. Tax Accounting Differences • Contributions and Distributions • Ownership Changes • Prior-Year Reporting
Your offshore partnership may maintain its books under foreign accounting standards, distribute money without clear supporting statements, or make business decisions that affect your U.S. tax position without your direct involvement.
You may also have contributed property, increased your investment, or transferred part of your ownership interest.
Even when the business activity occurs entirely overseas, the financial records and transactions may have important consequences for your U.S. tax returns and international reporting obligations.
Foreign Financial Statements May Not Answer U.S. Tax Questions
Partnership records prepared for foreign regulatory or tax purposes may not provide all the information needed to determine a U.S. partner's income, deductions, gains, losses, and other reportable items.
Differences in accounting methods, tax classifications, reporting periods, and the treatment of particular transactions may require additional analysis.
A foreign partnership's reported profit is not necessarily identical to the amount a U.S. partner must report under U.S. federal tax law.
Contributions, Distributions, and Ownership Changes Deserve Separate Attention
Capital contributions, transfers of property, distributions, acquisitions, and dispositions may have consequences beyond the partnership's ordinary operating income.
Certain transactions can also affect the applicable Form 8865 reporting category or create additional disclosures.
The details matter: the nature of the property, the parties involved, the ownership percentages before and after a transaction, and the applicable U.S. tax treatment may all influence the result.
Incomplete Records Can Affect More Than One Tax Year
When a partnership has not provided complete information, errors or omissions may extend across multiple returns.
A meaningful review may require reconstructing ownership changes, examining transaction histories, reconciling foreign financial statements, and identifying what was previously reported to the IRS.
Allen Barron's coordinated legal, tax, and accounting approach is designed to address these interconnected issues rather than evaluating an isolated form without understanding the underlying business activity.
The Most Important Step You Can Take Right Now.
It is important to understand where you are in this moment, the information you might be missing, the best actions and communications to undertake (and those to avoid), and the most productive and effective steps you can take to protect your interests and accomplish your objectives.
We invite you to a free, substantive consultation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling 866-631-3470.
Many offshore partnership transaction and financial reporting issues are influenced not only by what has already happened, but by what happens next. An early conversation with our firm can help you better understand your position, your risks, your opportunities, and the actions that may improve the likelihood of achieving a successful outcome.
THE MOST IMPORTANT THING YOU NEED TO KNOW RIGHT NOW
The greatest risk you face—and your greatest opportunity to protect your interests and achieve a successful outcome—are not weeks or months from now, during an IRS examination, or after a reporting problem has become a tax controversy. They exist RIGHT NOW.
If you have an ownership interest in a foreign trust or offshore partnership, your circumstances may involve U.S. tax obligations you do not fully understand, financial records you do not control, transactions whose consequences have not been evaluated, or previous filings that may require attention.
The decisions you make, the actions you take, and the communications you send in the coming hours and days WILL substantially affect the outcome.
There are actions you should take and communications you should make. There are also actions and communications you should avoid because they can adversely affect your interests, increase your exposure, or limit the options available to you.
Should you contact your foreign trustee or business partners? Request additional records? Authorize a distribution or transfer? Respond to an IRS inquiry? Submit missing information returns or amend previous tax filings?
How can you know the difference between an action that protects your interests and one that may make your situation more difficult?
That is why you need the experience, judgment, and guidance of Janathan Allen and her firm, Janathan L. Allen, APC, working in coordination with the legal, tax, and accounting professionals at Allen Barron.
Janathan can help you understand your actual circumstances, identify the information that matters, evaluate your obligations and available options, and determine which actions and communications will best protect your interests as you move forward.
This is why Janathan Allen and her firm offer a free, substantive, and private consultation. We invite you to discuss your foreign trust or offshore partnership, your concerns and objectives, the decisions confronting you, and the steps you should consider taking—or avoiding—RIGHT NOW.
You can reach us through the chat module on this page, our contact form, or by calling 866-631-3470.
Why You Need to Speak With Experienced International Tax Attorney Janathan Allen Before Taking Your Next Step
The law establishes your rights, responsibilities, reporting obligations, and potential consequences. But the law cannot independently examine your trust agreement, determine what your foreign trustee has actually done, reconcile offshore partnership financial records, or evaluate the decisions confronting you.
Janathan Allen and her firm provide the individualized legal counsel necessary to connect those requirements to your circumstances.
That distinction is especially important when foreign legal arrangements, U.S. tax classifications, financial transactions, and information-reporting obligations overlap.
An action that appears reasonable under the laws governing a foreign trust or partnership may have different consequences under U.S. tax law. A distribution, loan, contribution, change in ownership, or communication with a foreign fiduciary may create questions that should be understood before you proceed.
Janathan can help you distinguish what is known from what remains uncertain, identify information that should be obtained, and develop a deliberate approach to protecting your interests.
Understand Your U.S. Tax and Reporting Position Before Making Additional Transactions
A foreign trust's legal structure does not necessarily establish its treatment under U.S. tax law. Likewise, an offshore entity described as a partnership in another country may be classified differently for U.S. federal tax purposes.
Your ownership rights, degree of control, beneficiary status, prior transfers, distributions, and financial activity can affect the analysis.
Depending on your circumstances, Forms 3520, 3520-A, 8865, or other international reporting requirements may be relevant.
Before transferring additional property, changing ownership arrangements, accepting distributions, or authorizing new transactions, it is important to understand how those decisions may affect your position.
Janathan Allen can help you evaluate the structure and the contemplated action together—before you create consequences that may be difficult to reverse.
Preserve the Documents and Financial Information That May Determine Your Options
Foreign trustees, partnership managers, accountants, financial institutions, and advisers may each possess different pieces of the information needed to understand your circumstances.
Relevant materials may include trust agreements and amendments, partnership agreements, ownership records, financial statements, contribution and distribution histories, loan documents, correspondence, and prior U.S. and foreign tax filings.
Preserve the records you already possess. Do not assume that missing information is unimportant simply because it is held overseas.
Before requesting explanations or additional documents, consider what information is needed, who controls it, and how the request should be communicated.
Janathan Allen and the Allen Barron team can help identify the records necessary to understand your position, coordinate their legal and accounting review, and determine what additional information should be obtained.
Understand What to Communicate—and What Not to Communicate—Before You Act
Communications with foreign trustees, business partners, financial institutions, accountants, and the IRS can become part of the record of your transactions and reporting history.
An incomplete explanation, an unsupported characterization of a transaction, or an attempt to correct a filing before the underlying facts are understood can complicate the situation.
This does not mean you should ignore legitimate requests, disregard filing deadlines, or withhold information you are legally required to provide.
It means you should understand your obligations and the consequences of your communications before deciding what to say, what to provide, and when to act.
Janathan Allen can help you evaluate the purpose, timing, content, and legal significance of important communications, including those involving previous reporting omissions or IRS inquiries.
Address Potential Reporting Problems Before They Become More Difficult to Resolve
You may discover that a foreign trust was never properly reported, that an offshore partnership's financial information was incomplete, or that transactions from previous years were not accurately reflected on your U.S. tax returns.
Some international information-reporting requirements carry substantial penalties, even where additional income tax is not owed.
The appropriate response depends on the actual filing obligations, the nature and duration of any omissions, the information available, the reasons the problem occurred, and whether the IRS has already initiated an examination or inquiry.
Do not assume that immediately submitting missing forms or amended returns is necessarily the best first step.
The immediate priority is to establish the facts, understand the applicable obligations, identify available correction procedures or other responses, and make informed decisions about what should happen next.
Janathan Allen and her firm can help you assess these considerations before potentially consequential filings or communications are undertaken.
Protect Your Options Before Choosing Your Ultimate Strategy
You may not yet know whether your foreign trust or offshore partnership requires restructuring, whether prior tax filings need correction, whether a trustee or partner must provide additional information, or whether an IRS matter requires a formal response.
You do not have to resolve every one of those questions before taking meaningful steps to protect yourself.
What matters RIGHT NOW is understanding your position, preserving relevant information, identifying immediate risks, and avoiding decisions that unnecessarily restrict your future options.
Janathan Allen and her firm can help you establish priorities, determine appropriate next steps, and develop a strategy grounded in your circumstances and objectives.
The objective is not simply to react to a potential tax problem. It is to protect your interests while preserving the greatest practical opportunity for a successful outcome.
We invite you to a complimentary and substantive conversation regarding your foreign trust or offshore partnership, your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling 866-631-3470.
You Need International Planning and Tax Experience and Skill When the Stakes Are Significant
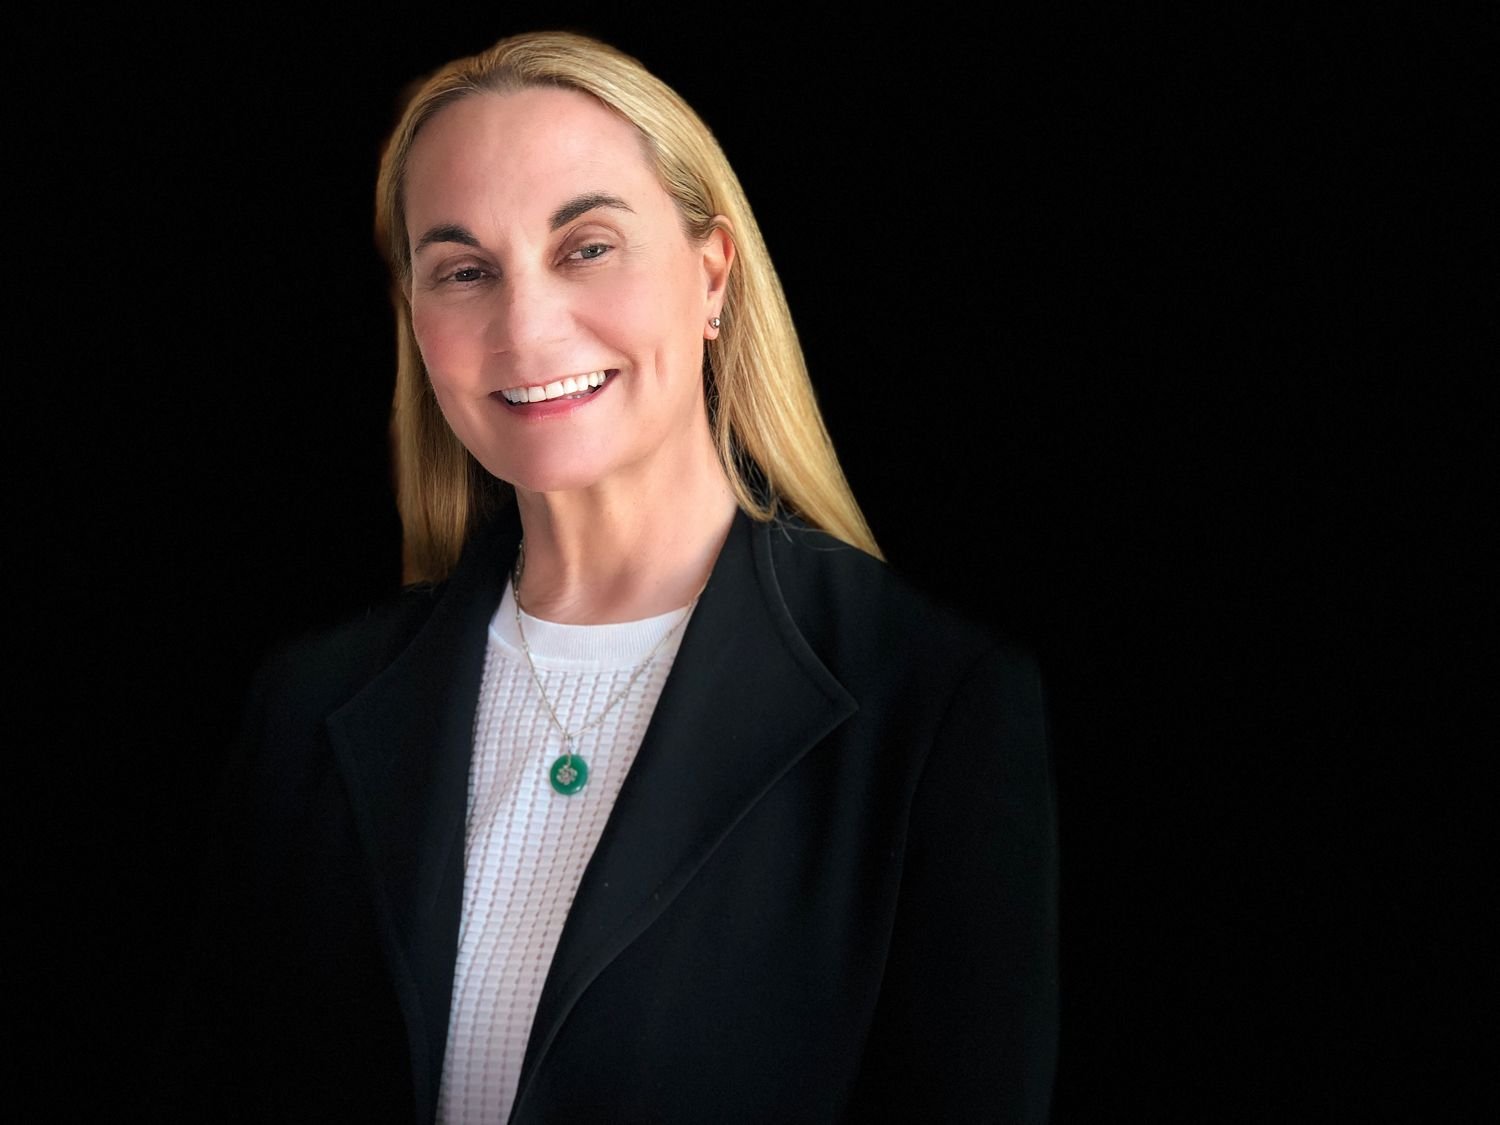 Janathan L. Allen has decades of experience advising and representing businesses, business owners, investors, and individuals in complex domestic and international tax matters, including foreign trusts, offshore partnerships, international ownership structures, cross-border investments, U.S. tax reporting obligations, and disputes involving the Internal Revenue Service.
Her experience encompasses both proactive international tax planning and high-consequence tax controversies, where foreign legal arrangements, U.S. tax classifications, ownership and control, financial transactions, and reporting requirements intersect.
Working in coordination with the legal, tax, and accounting professionals at Allen Barron, Janathan Allen and Allen Barron help clients understand their obligations, evaluate their risks and opportunities, protect their interests, and make informed decisions before consequential actions are taken.
Allen Barron also assists clients who are planning ahead, seeking to come into compliance, or addressing international tax concerns before they become larger disputes. Tax planning, voluntary compliance, offshore reporting, expatriate tax issues, international investments, and cross-border business activities often benefit from early, coordinated guidance. Taking the right steps now may help reduce exposure, preserve options, and prevent avoidable tax, legal, accounting, and financial consequences.
The initial consultation is a complimentary, substantive, confidential discussion designed to help you better understand your current position, the issues that may require immediate attention, and the strategies that may help protect your financial and business interests moving forward.
You are invited to engage the chat module on this page, contact Allen Barron, or call (866) 631-3470 to schedule a free, substantive consultation.
Learn more about Janathan L. Allen, APC and Allen Barron’s integrated tax, legal, accounting and business consulting services and how an integrated approach may help identify risk, protect assets, reduce unnecessary exposure, and support your long-term business and financial objectives.