Welcome. Before You Begin:
Understanding your IRS Voluntary Disclosure Program options, potential tax exposure, prior reporting issues, and the steps available to bring your tax affairs into compliance requires focus. We are here to help.
As you evaluate the information below, you remain in complete control of your timeline and decisions.
If this material confirms a risk, raises a concern, or if you require immediate clarification, there are multiple ways to easily connect with us for free insight to learn more. You do not need to interrupt your reading or navigate away from this page to secure that guidance:
- Direct Phone Access: Our phone number is anchored in the upper right menu.
- Continuous Chat Support: Actively present on your screen for immediate connection.
- Secure Inquiry: The “Contact Us” menu option above is a direct, private way to connect with us or request a free consultation.
This firm provides a substantive, confidential consultation at no cost. You are invited and encouraged to read the material ahead to orient yourself. When you’re ready to ask questions, or discuss the specific facts of your situation, we invite you to reach out.
Which of These IRS Voluntary Disclosure Situations Are You Facing?
People considering the IRS Voluntary Disclosure Program often arrive here from very different circumstances. You may already know that income or other information was intentionally left off prior tax filings. You may instead be uncertain about how the IRS would view what happened. You may have foreign accounts or business interests that were never properly reported, or you may simply know that prior filings need to be corrected and are unsure which compliance option applies.
The circumstances surrounding what happened, what was previously filed, and whether the IRS has already received information about the issue can affect the options available to you.
Review the situations below and select the one that most closely reflects the issue you are facing.
I Know That I Intentionally Failed to Report Income or Tax Information
You know that something was intentionally omitted, understated, or inaccurately reported on prior tax filings.
- Income was deliberately left off a tax return.
- Required tax returns or reports were intentionally not filed.
- Information provided on prior filings was knowingly incomplete.
- Deductions or expenses may have been intentionally overstated.
- You now want to address the issue before taking further action.
Learn More →
I Am Concerned My Conduct May Be Considered Willful
You know there is a reporting problem, but you are uncertain how the facts and your prior actions may be characterized.
- You knew there may have been a reporting requirement but did not fully address it.
- You received advice or information about an obligation that was not followed.
- Prior filings contain omissions that continued for more than one year.
- You are concerned about statements, communications, or decisions made at the time.
- You do not know whether VDP or another compliance procedure is appropriate.
Learn More →
I Have Unreported Foreign Accounts, Assets, or Income
You have financial interests outside the United States and believe some portion of the required U.S. tax or information reporting may not have been completed.
- Foreign income may not have been reported on U.S. tax returns.
- Foreign financial accounts may not have been properly disclosed.
- You own or have owned an interest in a foreign business or entity.
- International information returns or FBARs may be missing or incomplete.
- The reporting issue may extend across several tax years.
Learn More →
My Business Has Unreported Income or Other Tax Compliance Problems
The potential noncompliance involves a corporation, partnership, business activity, or transactions connected with a business you own or control.
- Business income may have been omitted or understated.
- Business returns may contain information you now believe was inaccurate.
- Transactions between you and the business may require closer review.
- The problem may affect both the business and your individual tax filings.
- Multiple years of business records and tax returns may need to be reconstructed or reviewed.
Learn More →
I Am Concerned the IRS May Already Know About the Problem
You have reason to question whether the IRS has already obtained information concerning the income, accounts, transactions, or filings at issue.
- You received correspondence or another communication from the IRS.
- A related individual or business is being examined or investigated.
- A financial institution, business, or other third party may have reported relevant information.
- The issue involves foreign accounts or transactions subject to third-party reporting.
- You are uncertain whether voluntary disclosure remains available to you.
Learn More →
I Need to Correct Prior Tax Filings but Do Not Know Whether VDP Is the Right Option
You know something in your prior tax or reporting history needs attention, but you do not yet know which compliance procedure fits the circumstances.
- Prior tax returns may need to be amended.
- Required returns or information filings may never have been submitted.
- You have recently discovered an issue involving earlier tax years.
- You are considering VDP, Streamlined Filing Compliance Procedures, delinquent filings, or another approach.
- You want to understand the facts and available options before making corrective filings.
Learn More →
I Know That I Intentionally Failed to Report Income or Tax Information
If you know that income, transactions, accounts, or other required tax information were intentionally omitted from prior filings, the issue should be evaluated differently from an inadvertent reporting mistake.
The IRS Voluntary Disclosure Practice is intended for taxpayers whose noncompliance may have been willful. However, knowing that something was intentionally omitted does not mean you should assume VDP is automatically the appropriate next step. The nature of the conduct, the tax years involved, the returns and information reports affected, and what the IRS may already know should be established before a disclosure strategy is selected.
The first objective is to develop an accurate picture of what happened. That may require reviewing previously filed returns, identifying omitted income or transactions, determining which filings were not made, and reconstructing records for the affected years.
The decision to enter VDP should follow that analysis—not precede it.
Next Action steps
If you know information was intentionally omitted from prior tax filings, speak with an experienced tax attorney before submitting amended returns, contacting the IRS, or attempting to correct the issue independently.
We invite you to a complimentary and substantive conversation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling (866) 631-3470.
I Am Concerned My Conduct May Be Considered Willful
One of the most important questions in determining how to address prior tax noncompliance is whether the conduct involved may be considered willful.
You may not believe that you deliberately attempted to evade a tax obligation. The underlying history, however, may include information you received, questions you were asked, prior reporting decisions, repeated omissions, or other circumstances that need to be examined before reaching a conclusion.
Do not label your own conduct as either willful or non-willful before the underlying facts have been carefully reviewed.
That distinction can affect which compliance procedures may be available. VDP and the Streamlined Filing Compliance Procedures address materially different circumstances. Choosing a procedure first and attempting to fit the facts into it afterward can unnecessarily limit your options.
The better starting point is the history itself: what you knew, what you were advised, what was filed, what was omitted, and why the reporting problem occurred.
Next Action steps
If you are uncertain how your prior conduct may be characterized, obtain legal guidance before making a certification, submitting corrective filings, or communicating your position to the IRS.
We invite you to a complimentary and substantive conversation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling (866) 631-3470.
I Have Unreported Foreign Accounts, Assets, or Income
Foreign accounts and investments can create several different U.S. tax and information-reporting obligations. Discovering that an account, asset, business interest, or foreign source of income was not properly reported does not by itself determine which compliance procedure should be used.
The first task is to determine what was owned or controlled, which reporting obligations applied, which years are affected, what income was generated, and what was actually reported.
That review may involve foreign financial accounts, FBARs, foreign business interests, international information returns, U.S. income tax returns, and records maintained outside the United States.
The circumstances that produced the reporting failure also matter. A taxpayer whose failure was non-willful may have options that are different from those available when the underlying conduct was willful.
The existence of an offshore reporting problem and the method used to correct that problem are two separate questions.
Next Action steps
Before filing delinquent FBARs, amending tax returns, or selecting an offshore compliance procedure, establish the scope and history of the reporting issue.
We invite you to a complimentary and substantive conversation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling (866) 631-3470.
My Business Has Unreported Income or Other Tax Compliance Problems
Voluntary disclosure is not limited to taxpayers with offshore bank accounts. A potential disclosure may involve a corporation, partnership, closely held business, business owner, or a combination of related taxpayers and entities.
The first question is not simply how much income went unreported. It is necessary to understand the transactions, records, entities, tax returns, and individuals involved and determine how the reporting problem developed.
Business-related matters can require reconstruction of accounting records and prior returns as well as legal analysis of the underlying conduct. Where foreign businesses or transactions are involved, additional international reporting and accounting issues may also have to be addressed.
The business and its owners should not automatically be treated as a single compliance problem. The filings, conduct, and potential exposure associated with each taxpayer or entity need to be identified.
This is one of the circumstances in which coordinated legal and accounting analysis can be particularly important.
Next Action steps
If the reporting issue involves a business, related entity, or transactions between a business and its owners, assemble the available tax returns and accounting records before attempting corrective filings.
We invite you to a complimentary and substantive conversation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling (866) 631-3470.
I Am Concerned the IRS May Already Know About the Problem
Timing can materially affect whether a voluntary disclosure remains available.
If you have received an IRS communication, learned that a related taxpayer or business is under examination, or have another reason to believe the government may already possess information concerning the issue, do not assume that you can simply make a voluntary disclosure before responding.
The circumstances need to be established first. That includes identifying what communication has been received, whether an examination or investigation has begun, what information may have been obtained from third parties, and what deadlines currently apply.
VDP has specific requirements governing whether a disclosure is timely. The fact that you have not personally discussed the underlying issue with an IRS representative does not, standing alone, establish that voluntary disclosure remains available.
This is a situation where what has already happened may be just as important as what you do next.
Next Action steps
Preserve every IRS notice, letter, request, and related communication. Do not make assumptions about VDP eligibility or provide an explanation of the underlying conduct before the situation has been evaluated.
If you are concerned the IRS may already know about the issue, Allen Barron can review what has occurred and help determine what options remain available. We invite you to a complimentary and substantive conversation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling (866) 631-3470.
I Need to Correct Prior Tax Filings but Do Not Know Whether VDP Is the Right Option
Discovering a problem in prior tax filings does not automatically mean that you need to enter the IRS Voluntary Disclosure Practice.
Depending upon what happened and why, the appropriate response may involve VDP, Streamlined Filing Compliance Procedures, amended returns, delinquent information filings, FBAR compliance, or another method of addressing the underlying issue.
The compliance procedure should be selected only after the facts have established what needs to be corrected and why the problem occurred.
Start by identifying the affected years and gathering the returns, financial records, foreign account information, entity records, and other documents necessary to reconstruct the reporting history. Then determine what was missing or inaccurate and evaluate the circumstances surrounding the failure.
That process allows the available alternatives to be compared before representations are made to the IRS or corrective filings are submitted.
You do not need to know which program applies before asking for help. Determining that is part of the work.
Next Action steps
If you know prior filings need attention but are uncertain how to proceed, avoid choosing a compliance program based solely upon what appears to offer the lowest penalty or simplest filing process.
Allen Barron can help establish the facts, identify the reporting issues, and evaluate which available compliance approach fits those circumstances. We invite you to a complimentary and substantive conversation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling (866) 631-3470.
The Most Important Thing You Need to Know Right Now
The most important thing you need to know right now is that the decisions you make before entering the IRS Voluntary Disclosure Practice can directly affect the options available to you afterward.
VDP is not simply a method for filing corrected tax returns or paying previously unpaid tax. It is a specific compliance process for taxpayers whose prior conduct may have been willful. Before deciding whether to enter that process, you need to understand what happened, what needs to be corrected, what the IRS may already know, and whether VDP is the appropriate procedure for your circumstances.
Your immediate objective is not to make a disclosure. It is to establish the facts necessary to determine whether, when, and how a disclosure should be made.
Do Not Contact the IRS or Attempt to Explain What Happened Before You Have Legal Guidance
When you discover a serious tax reporting problem, there can be a natural desire to correct it immediately. That does not mean the first step should be a telephone call, letter, amended return, or explanation to the IRS.
What you say about what happened, what you knew, and why prior filings were incomplete can become important when willfulness and the appropriate compliance procedure are evaluated.
Establish the facts and obtain legal guidance before communicating your explanation of what occurred.
Do Not Decide for Yourself That Your Conduct Was Willful or Non-Willful
Willfulness can be central to the decision between VDP and other compliance alternatives. It should not be reduced to whether you personally believe you intended to violate the tax laws.
The history may include prior professional advice, communications, tax returns, reporting patterns, foreign account documentation, business records, and actions taken over several years.
Do not begin by choosing the label. Begin by reconstructing the facts.
Determine Whether a Voluntary Disclosure Is Still Timely
The availability of VDP can depend upon what has already occurred.
An IRS examination or investigation, information received by the government from another source, or other developments may affect whether a disclosure can still qualify as timely.
If you have received an IRS notice, examination letter, request for information, or another communication that may relate to the underlying issue, preserve it and obtain legal guidance promptly.
Do not assume that VDP remains available simply because you have not yet discussed the specific problem with the IRS.
Preserve and Begin Organizing the Records Needed to Establish What Happened
A voluntary disclosure may require reconstructing several years of tax and financial history. Begin preserving the information that can establish:
- Tax returns and information returns previously filed
- Bank, investment, and financial account records
- Foreign account and FBAR records
- Business and entity accounting records
- Records of income, transactions, ownership, and distributions
- Communications with accountants, tax preparers, financial professionals, and other advisers
Do not alter, discard, recreate, or attempt to make the historical record look cleaner than it actually is.
The objective is to establish an accurate and supportable history of what occurred.
Do Not Select a Compliance Procedure Based Primarily Upon the Penalty
VDP, Streamlined Filing Compliance Procedures, delinquent filings, amended returns, and other potential approaches are not interchangeable methods for obtaining the most favorable penalty.
Each applies to particular facts and circumstances.
The appropriate compliance path should be determined by the facts first. The potential tax, interest, and penalty consequences can then be evaluated within that framework.
Protect Your Options Before You Begin
You do not need to determine whether VDP is appropriate before speaking with Allen Barron. That determination is part of the legal and tax analysis.
Allen Barron can help reconstruct what occurred, identify the filings and tax years involved, evaluate the circumstances surrounding the noncompliance, and determine which available compliance options should be considered.
The objective at this stage is to understand your position clearly enough to make the next decision deliberately rather than reactively.
We invite you to a complimentary and substantive conversation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling (866) 631-3470.
What Is the IRS Voluntary Disclosure Practice and Who May Qualify?
The IRS Voluntary Disclosure Practice, commonly referred to as VDP, provides a process for taxpayers whose tax or tax-related noncompliance was willful to come forward, disclose what occurred, and work toward resolving their outstanding federal tax and reporting obligations.
VDP is administered through IRS Criminal Investigation. A timely, truthful, and complete voluntary disclosure is considered by IRS Criminal Investigation when determining whether to recommend criminal prosecution. Participation in VDP does not provide an automatic guarantee against prosecution, but a qualifying voluntary disclosure may result in prosecution not being recommended.
VDP is not limited to offshore bank accounts or FBAR violations. Depending upon the circumstances, a voluntary disclosure may involve unreported domestic or foreign income, unfiled returns, inaccurate tax returns, overstated deductions, foreign financial accounts, international information reporting, businesses and related entities, or other willful failures to comply with federal tax obligations.
The IRS Voluntary Disclosure Practice Is Intended for Potentially Willful Tax Noncompliance
VDP is designed for taxpayers whose failure to comply with tax or tax-related obligations was willful rather than the result of an inadvertent mistake.
Individuals and entities may potentially seek participation in VDP. The underlying conduct can involve intentionally failing to report income, failing to pay tax, failing to submit required returns or reports, or knowingly providing inaccurate information on prior filings.
The existence of a reporting error alone does not establish that VDP is appropriate. The circumstances that produced the noncompliance must be understood first.
This is one reason the analysis of willfulness should occur before a taxpayer selects a compliance procedure or begins making corrective filings.
A Voluntary Disclosure Must Be Truthful, Timely and Complete
The IRS requires a voluntary disclosure to be truthful, timely, and complete. Participation also requires the taxpayer to cooperate with the IRS in determining the correct tax liability and resolving the affected tax and reporting obligations.
This means VDP should not be viewed simply as an opportunity to amend selected returns or disclose only the portion of a problem that has already been discovered.
A taxpayer entering VDP must be prepared to disclose the relevant noncompliance and cooperate in establishing the correct tax and reporting history.
The process may require substantial supporting documentation, corrected or delinquent filings, financial and accounting records, and information concerning individuals or entities connected with the noncompliance.
Timing Can Determine Whether VDP Remains Available
A voluntary disclosure must occur before certain government actions or sources of information eliminate its timeliness.
Under the current IRS rules, a disclosure is considered timely when it is received before the IRS has:
Commenced a civil examination or criminal investigation;
Received information from a third party alerting the IRS to the taxpayer's noncompliance; or
Acquired information directly related to the taxpayer's specific noncompliance through a criminal enforcement action.
This is why a taxpayer who believes the IRS may already know about the problem should determine what has occurred before assuming VDP remains available.
Receiving information from a financial institution, another governmental agency, an informant, or another enforcement source may matter even when the taxpayer has not personally been contacted about the specific noncompliance.
VDP May Not Be the Appropriate Procedure for Non-Willful Conduct
VDP is intended to address willful tax noncompliance. A taxpayer whose reporting failure resulted from an error, misunderstanding, negligence, or other non-willful conduct may have other methods available to correct prior filings and come into compliance.
Those alternatives may include amended or delinquent returns and, in qualifying international reporting situations, the IRS Streamlined Filing Compliance Procedures.
The objective is not to choose the program that appears most favorable and then characterize the taxpayer's conduct accordingly. The facts should establish the nature of the noncompliance, and the appropriate compliance procedure should follow from that analysis.
If there is uncertainty about whether prior conduct was willful or non-willful, that question should be carefully evaluated before submitting a VDP application, making a non-willfulness certification, or attempting to correct the underlying filings.
Willful Versus Non-Willful Conduct: Why the Distinction Matters
Whether prior tax noncompliance was willful or non-willful can fundamentally affect the options available to correct it.
The IRS Voluntary Disclosure Practice is intended for taxpayers whose failure to comply with tax or tax-related obligations was willful. The Streamlined Filing Compliance Procedures and other corrective filing options may be available when qualifying noncompliance was non-willful.
This makes the determination of willfulness one of the most important decisions that may be made before selecting a compliance procedure.
Willfulness Is Based Upon the Facts and Circumstances
The question is not resolved simply by asking whether you intended to break a tax law.
The analysis may involve what you knew about the reporting obligation, professional advice you received, information provided to accountants or tax preparers, prior tax filings, questions you were asked, reporting patterns over multiple years, financial records, and actions taken after learning that a reporting requirement may exist.
Conduct involving deliberate actions is different from an inadvertent mistake. However, the circumstances surrounding a taxpayer's failure to act can also become important when willfulness is evaluated.
The complete history should be reconstructed before reaching a conclusion about how the conduct should be characterized.
A Non-Willful Reporting Failure May Lead to Different Compliance Options
If the underlying failure resulted from negligence, inadvertence, mistake, or a good-faith misunderstanding of applicable requirements, VDP may not be the appropriate compliance procedure.
In qualifying international tax matters, the Streamlined Filing Compliance Procedures may provide a path for taxpayers whose failure to report foreign financial assets and associated income was non-willful. Other circumstances may be addressed through amended returns, delinquent returns, or other corrective procedures.
Different compliance procedures exist because different factual circumstances require different solutions.
Do Not Choose the Compliance Procedure Before Resolving the Willfulness Question
A taxpayer should not decide to use VDP simply because the underlying problem appears serious. Likewise, a taxpayer should not select a non-willful procedure merely because its potential consequences appear more favorable.
Both approaches begin with the desired outcome rather than the underlying facts.
The appropriate sequence is to establish what happened, evaluate the circumstances surrounding the noncompliance, determine how those facts affect the available options, and then select the appropriate compliance procedure.
The facts should determine the compliance strategy—not the other way around.
How Does the IRS Voluntary Disclosure Process Work?
The current IRS Voluntary Disclosure Practice begins with Criminal Investigation and uses Form 14457, Voluntary Disclosure Practice Preclearance Request and Application.
The process occurs in stages. Preclearance is only the beginning of the process and does not itself guarantee acceptance into VDP.
Step One: Request Preclearance From IRS Criminal Investigation
The taxpayer begins by submitting Part I of Form 14457 to IRS Criminal Investigation.
Preclearance allows Criminal Investigation to determine whether information already available to the government prevents the taxpayer from proceeding with a voluntary disclosure.
Receiving preclearance indicates that the taxpayer may proceed to the application stage. It does not constitute preliminary acceptance into VDP.
Step Two: Submit the Voluntary Disclosure Application
After receiving a preclearance letter, the taxpayer generally has 45 days to submit Part II of Form 14457.
Part II requires substantially more information concerning the taxpayer and the underlying noncompliance. The taxpayer must provide a complete description of the conduct involved and disclose information necessary for Criminal Investigation to evaluate the voluntary disclosure.
If additional time is required, the IRS currently permits a taxpayer to request one extension of up to 45 days. Approval is determined on a case-by-case basis.
This is one reason the factual and financial history should be substantially understood before the VDP process is started.
Step Three: IRS Criminal Investigation Determines Preliminary Acceptance
IRS Criminal Investigation reviews the information provided in Part II and determines whether the taxpayer will receive preliminary acceptance into the Voluntary Disclosure Practice.
If preliminary acceptance is granted, the taxpayer receives a Preliminary Acceptance Letter and the matter is forwarded to the civil side of the IRS.
Preliminary acceptance does not complete the voluntary disclosure. It moves the matter into the examination and resolution phase.
Step Four: Cooperate With the IRS Civil Examination
Once the case is assigned, an IRS civil examiner contacts the taxpayer or the taxpayer's representative.
The taxpayer is required to cooperate with the examination, provide requested documents and information, and establish the correct tax and reporting obligations for the applicable disclosure period.
Corrected or delinquent tax returns and other required filings are addressed through this process rather than simply being submitted independently before the VDP examination begins.
The IRS also requires the taxpayer to acknowledge the willful failure to comply with applicable tax or tax-related obligations.
Step Five: Resolve the Tax, Reporting and Penalty Issues
The examination ultimately addresses the corrected tax liability, interest, applicable penalties, delinquent or amended returns, and other reporting obligations associated with the disclosure.
Where foreign financial accounts or international entities are involved, the process may also require FBARs and international information returns.
VDP is therefore not a single filing. It is a structured process of disclosure, reconstruction, examination, cooperation, corrective reporting, and resolution.
What Must Be Reconstructed and Filed During VDP?
One of the most substantial parts of a voluntary disclosure can occur after the initial decision to pursue VDP.
The taxpayer and professional team must establish an accurate financial and tax history for the applicable disclosure period and prepare the records and filings necessary to support that history.
In a complex VDP matter, determining what happened can require as much work as determining how the law applies to what happened.
Prior Tax Returns and Missing Filings Must Be Identified
The process begins by determining which federal tax returns were filed, which were not filed, and which previously filed returns contain information that needs to be corrected.
That review may involve individual income tax returns as well as returns associated with corporations, partnerships, trusts, estates, employment taxes, or other taxable entities or obligations.
The objective is to establish an accurate year-by-year record of what was reported and what should have been reported.
Income and Financial Records May Need to Be Reconstructed
Bank records, investment statements, business accounting records, transaction histories, ownership records, payroll information, financial statements, and other source documents may be required to reconstruct taxable income and establish the correct liability.
Records may be incomplete, maintained by several institutions, located outside the United States, or prepared under accounting systems that were not designed for U.S. tax reporting.
Where complete historical documentation cannot be obtained, the IRS expects taxpayers to make reasonable efforts to obtain the missing information. The circumstances may require reasonable estimates supported by an explanation of how those estimates were developed.
The objective is not to create a perfect historical record where one no longer exists. It is to develop an accurate, supportable reconstruction based upon the information reasonably available.
Foreign Financial Accounts May Require FBAR Analysis and Corrective Filings
When the disclosure involves foreign financial accounts, the taxpayer must identify the relevant accounts, ownership or authority over those accounts, applicable years, and account values.
The review must then determine which FBAR filings were required, which were filed, and which are delinquent or require correction.
FBAR issues should be coordinated with the broader voluntary disclosure rather than treated as an unrelated filing exercise.
Foreign Businesses and Other International Interests Can Add Another Layer of Reporting
A voluntary disclosure involving foreign corporations, partnerships, trusts, financial assets, gifts, inheritances, or other international interests may require additional U.S. information returns.
The accounting records maintained for a foreign business may also need substantial analysis before the information can be used to prepare accurate U.S. tax and information filings.
This can require coordination between legal analysis, U.S. tax reporting, international tax requirements, and the underlying accounting records.
Related Businesses and Taxpayers Must Be Evaluated Separately
A reporting problem involving a business owner may also involve the business itself, another entity, employment taxes, foreign entities, or other related taxpayers.
Each affected taxpayer, entity, tax return, and reporting obligation should be identified rather than assuming that correcting the individual's return resolves the entire matter.
This is particularly important where transactions moved between related entities or where the same underlying conduct affected multiple tax filings.
The Reconstruction Creates the Foundation for the VDP Resolution
The purpose of gathering and reconstructing this information is not simply to satisfy a document request.
It allows the taxpayer and counsel to understand the actual scope of the noncompliance, calculate the corrected tax obligations, prepare the necessary returns and reports, respond accurately during the examination, and evaluate the tax, interest, and penalty consequences of the disclosure.
A voluntary disclosure can only be as reliable as the factual and financial record upon which it is built.
What Taxes, Interest and Penalties May Apply Under the Current IRS Voluntary Disclosure Practice?
Entering the IRS Voluntary Disclosure Practice does not eliminate the underlying tax liability, interest, or applicable civil penalties.
VDP instead provides an established framework for taxpayers with potentially willful tax noncompliance to disclose what occurred, cooperate with the IRS, correct the affected filings, and resolve the resulting tax and reporting obligations.
The financial consequences of a voluntary disclosure depend upon the type of noncompliance involved, the tax years and taxpayers affected, and whether the matter includes foreign financial accounts, international information returns, businesses, or other tax obligations.
The following describes the penalty framework currently applicable to VDP matters. A separate proposed framework is discussed below because those proposed changes are not currently in effect.
Civil Fraud or Fraudulent Failure-to-File Penalties
Under the current VDP framework, a civil fraud penalty or fraudulent failure-to-file penalty generally applies to at least one year of every voluntary disclosure.
For income tax matters involving multiple years, the IRS generally applies the fraud or fraudulent failure-to-file penalty to the year within the disclosure period with the highest tax deficiency.
The civil fraud penalty is generally 75% of the portion of the underpayment attributable to fraud. A fraudulent failure-to-file penalty can also reach 75% under the applicable calculation.
Under the standard VDP penalty framework, applying the fraud penalty to one year is generally in lieu of accuracy-related and delinquency penalties for the other years within the disclosure period.
This framework assumes that the taxpayer complies with the requirements of VDP, including the obligation to cooperate fully with the IRS.
Related taxable entities can create additional consequences. If the voluntary disclosure involves both an individual and a related taxable entity, for example, the IRS may apply the applicable fraud penalty separately at the individual and entity levels.
FBAR Penalties
When a VDP matter includes FBAR noncompliance, the IRS treats the FBAR violations within the voluntary disclosure as willful and calculates penalties under the applicable IRS FBAR penalty guidelines.
The amount of an FBAR penalty can depend upon the account values, affected years, applicable penalty limitations, and other circumstances surrounding the violation.
FBAR penalties should therefore be calculated from the actual account history and applicable penalty rules rather than estimated using a simple percentage of the taxpayer's total foreign assets.
The FBAR component of a voluntary disclosure is handled in conjunction with the broader VDP examination but remains subject to the rules governing FBAR reporting and penalties.
International Information Return Penalties
A voluntary disclosure involving foreign corporations, partnerships, trusts, gifts, inheritances, financial assets, or other international interests may also involve delinquent or inaccurate international information returns.
Under the current VDP framework, penalties associated with failures to file international information returns are not automatically imposed in every case.
The IRS examiner considers the facts and circumstances of the matter, including the application of other penalties, when determining whether international information return penalties should be asserted.
This is another reason the complete international reporting history should be identified during the reconstruction of the voluntary disclosure.
Tax and Interest Remain Due
VDP does not eliminate the federal tax that should have been paid.
Corrected tax liabilities are determined during the examination, and interest generally accrues on unpaid tax in accordance with applicable law.
Other taxes or penalties may also apply depending upon the nature of the disclosure. Matters involving employment taxes, estates and gifts, excise taxes, or other specialized tax obligations can involve different penalty provisions and calculations.
The total financial exposure cannot be reliably determined until the affected years, taxpayers, entities, income, filings, accounts, and reporting obligations have been identified.
Payment of Tax, Interest and Penalties
Resolution of a VDP matter generally requires payment of the taxes, interest, and penalties determined through the examination or an acceptable arrangement for payment.
If a taxpayer cannot pay the full amount, the IRS may require detailed financial information to establish the taxpayer's ability to pay and evaluate whether an appropriate collection arrangement is available.
The inability to immediately pay the entire anticipated liability should therefore be evaluated as part of the voluntary disclosure strategy rather than used as a reason to ignore the underlying compliance problem.
Before entering VDP, the potential financial consequences should be modeled as accurately as the available information permits so that the taxpayer understands both the compliance process and the potential cost of resolving the matter.
Proposed Changes to the IRS Voluntary Disclosure Practice — Status as of September 2026
IMPORTANT: The following changes have been proposed by the IRS but are not the current VDP rules described above.
In December 2025, the IRS announced proposed changes to the Voluntary Disclosure Practice and opened a public comment period that ended March 22, 2026.
As of September 2026, the IRS continues to describe this framework as proposed. Taxpayers evaluating VDP should therefore distinguish between the rules currently in effect and changes the IRS has proposed but has not yet finalized.
The Proposed Penalty Framework Would Be Substantially Different
Under the IRS proposal, the existing VDP penalty structure would be replaced with a more standardized framework.
For amended returns, the proposal generally calls for a 20% accuracy-related penalty for each year in the disclosure period.
For delinquent returns, failure-to-file penalties would generally apply for each year, while failure-to-pay penalties would not.
Delinquent or amended FBARs would be subject to penalties for each applicable year, with the amounts subject to annual inflation adjustments.
Delinquent or amended international information returns could also result in penalties of up to $10,000 per return, per year under the proposed framework.
These are proposed terms. They should not be used to calculate the consequences of entering VDP under the rules currently in effect.
The Proposed Filing and Payment Process Would Also Change
The proposed procedure would change more than the penalty calculation.
The IRS proposal contemplates electronic submission of Form 14457. After preclearance, a taxpayer receiving conditional approval would generally be directed to submit the required returns and pay the amounts due within three months.
That would create a substantially different sequence from the current examination-based process and could place considerable importance on reconstructing the taxpayer's financial and reporting history before or immediately after beginning the VDP process.
For taxpayers with multiple entities, foreign accounts, international information returns, incomplete accounting records, or substantial historical reconstruction requirements, the practical demands of a three-month filing and payment period could be significant.
Taxpayers Should Base Today's Decisions Upon the Rules That Actually Apply
The existence of a proposed framework creates an understandable question: should a taxpayer proceed under the current VDP or wait to see whether the proposed changes become final?
There is no universal answer to that question.
A taxpayer's ability to make a timely voluntary disclosure can be affected by events outside the taxpayer's control, including IRS activity and information received by the government from other sources. Waiting for a potentially different penalty structure may therefore involve consequences that must be weighed against the taxpayer's present circumstances.
At the same time, the proposed rules should not be presented as though they are already available.
The decision should be based upon the taxpayer's actual circumstances, the VDP rules currently in effect, the status of the IRS proposal at the time the decision is made, and the risks associated with waiting.
Because the IRS may finalize, modify, or withdraw portions of the proposal, the status of these proposed changes should be verified immediately before a taxpayer makes a decision concerning voluntary disclosure.
Complex Voluntary Disclosures May Require Legal, Tax and Accounting Reconstruction
A complex voluntary disclosure is rarely just a matter of completing Form 14457.
Before corrected returns and information reports can be prepared, someone must determine what happened. Income may need to be reconstructed. Business transactions may need to be traced. Foreign accounts and entities may need to be identified. Previously filed returns must be compared with the underlying financial records. Missing filings must be identified, and information maintained under foreign accounting systems may need to be reconciled with U.S. tax and reporting requirements.
At the same time, legal decisions concerning willfulness, eligibility for VDP, the scope of the disclosure, communications with the IRS, and the taxpayer's obligations during the examination must be addressed.
These are not separate problems occurring at different times. In a complex VDP matter, the legal analysis, tax analysis, and accounting reconstruction directly affect one another.
The Financial History Must Be Reconstructed Before It Can Be Corrected
The starting point is often a collection of records that were never assembled for the purpose of making a voluntary disclosure.
Those records may include:
Previously filed U.S. tax returns and information returns
Domestic and foreign bank and investment statements
Business accounting records and financial statements
Ownership records for domestic and foreign entities
Records of distributions, transfers, loans, and other transactions
Foreign income and asset information
Previously filed or missing FBARs
Communications and records relating to prior tax preparation and reporting
The objective is to turn those records into a reliable year-by-year understanding of what occurred, what was reported, what was omitted, and what must now be corrected.
Until that history is established, it may be impossible to accurately calculate the tax liability, identify all required filings, or understand the full scope of the voluntary disclosure.
Foreign Businesses Can Create Additional Accounting and Reporting Challenges
A U.S. taxpayer with an ownership interest in a foreign business may have records prepared according to the accounting standards and practices used in another country.
Those financial records may not provide the information in the form required for U.S. tax reporting. Transactions may need to be traced, ownership and distributions established, income analyzed, and the underlying accounting information reconciled with the taxpayer's U.S. reporting obligations.
This can become particularly important when records are maintained under International Financial Reporting Standards, commonly known as IFRS, or another country's accounting standards.
The issue is not simply whether foreign financial statements exist. The information contained in those records must ultimately support accurate U.S. tax returns, international information returns, and the voluntary disclosure itself.
Multiple Taxpayers and Entities May Be Connected to the Same Underlying Conduct
A voluntary disclosure involving a business owner may extend beyond the individual's tax return.
The same underlying transactions can affect a corporation, partnership, trust, foreign entity, related taxpayer, or other reporting obligation. Money transferred between entities may have different consequences depending upon how the transaction was structured, recorded, and reported.
Each affected taxpayer and entity must therefore be identified and evaluated independently while still understanding how the transactions fit together.
Correcting one return does not necessarily correct the underlying compliance problem.
Legal Strategy and Accounting Reconstruction Should Develop Together
The accounting work establishes what happened financially. The legal analysis evaluates what those facts mean within the VDP process.
As records are reconstructed, new information may affect the understanding of the affected years, the amount of unreported income, the entities involved, the completeness of prior filings, and the circumstances surrounding the original noncompliance.
Those facts can affect legal decisions concerning willfulness, disclosure, cooperation with the IRS, and the resolution of the matter.
Conversely, the legal requirements of the voluntary disclosure determine which records, transactions, returns, and reporting obligations require additional accounting analysis.
When legal strategy and accounting reconstruction are coordinated from the beginning, each discipline informs the other as the factual record develops.
Allen Barron Integrates Legal, Tax and Accounting Experience
Allen Barron brings legal, tax, accounting, and international experience together when evaluating and resolving complex tax matters.
That integrated approach can be particularly valuable in a voluntary disclosure involving multiple tax years, businesses, foreign entities, offshore financial accounts, international information reporting, incomplete historical records, or financial information maintained outside the United States.
Rather than treating the legal analysis, accounting reconstruction, tax calculations, and corrective reporting as unrelated assignments, the objective is to develop a single reliable factual record that supports the decisions and filings required throughout the VDP process.
The value of an integrated approach is not simply convenience. It is the ability to understand how the legal, tax, accounting, and international reporting issues affect one another before consequential decisions are made.
Allen Barron provides a confidential consultation to discuss the circumstances surrounding a potential voluntary disclosure and the work that may be required to resolve it.
We invite you to a complimentary and substantive conversation regarding your situation, objectives, and concerns. You can reach out through the chat module on this page, our contact form, or by calling (866) 631-3470.
You Need Experienced Tax Counsel When the Stakes Are Significant
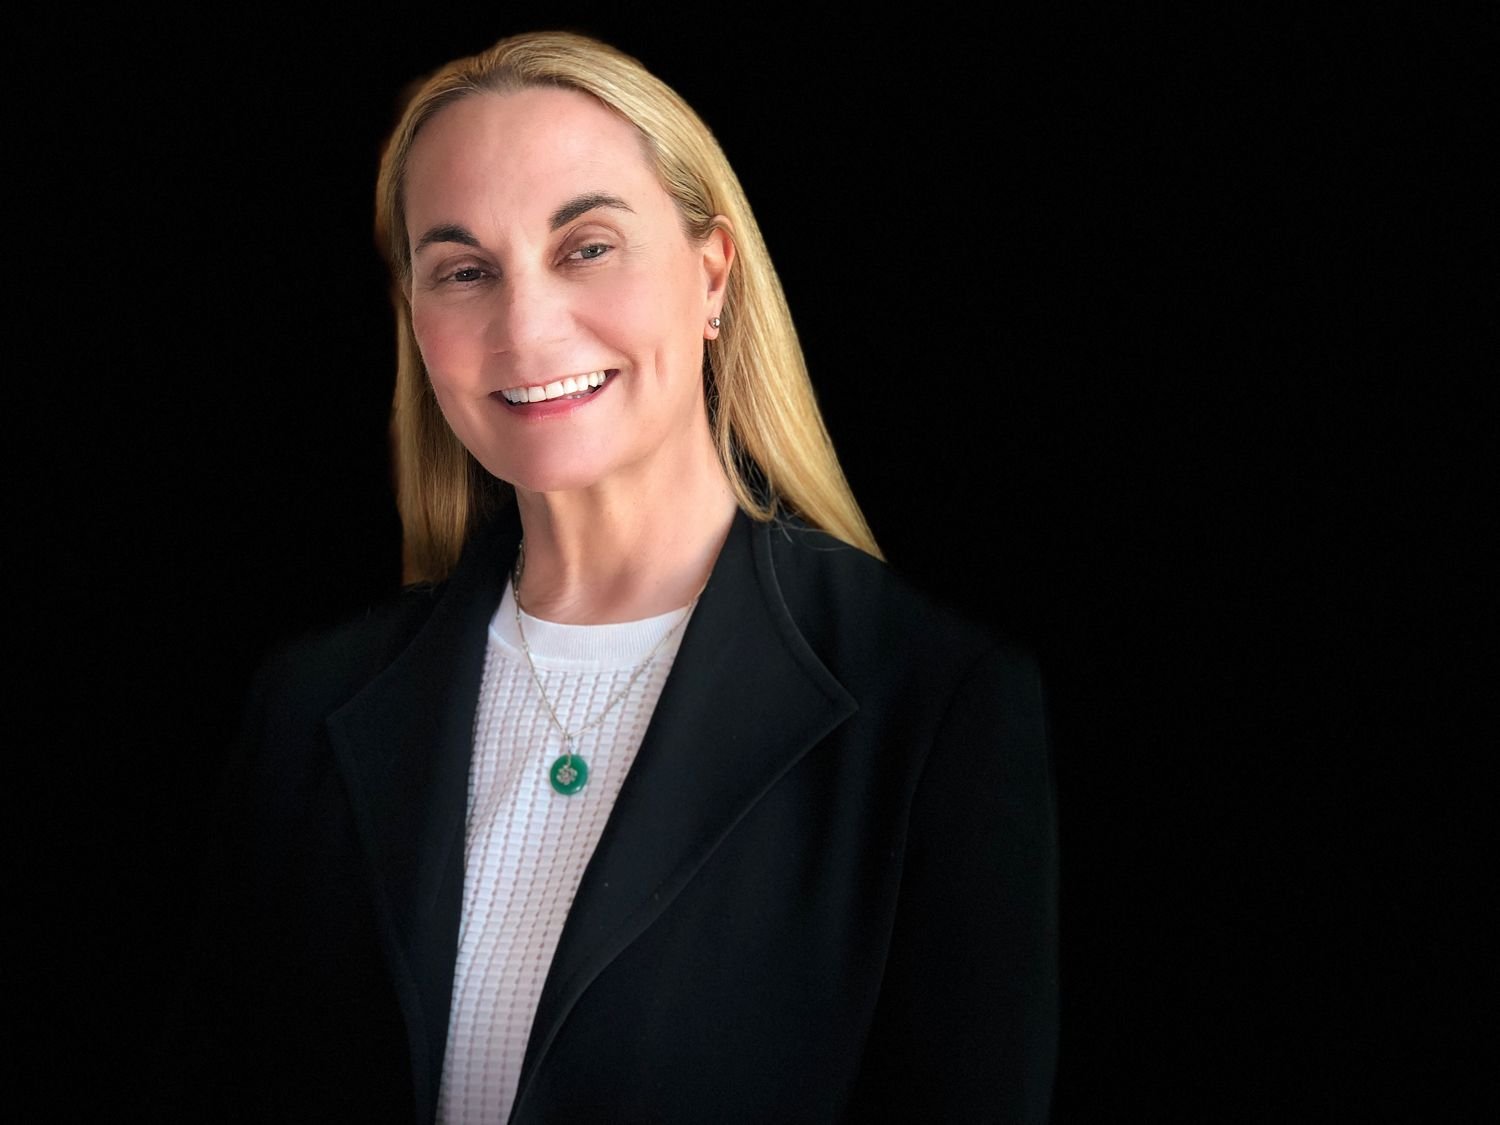 Janathan L. Allen has decades of experience representing businesses, business owners, investors, and individuals in IRS and California tax audits, payroll tax matters, worker misclassification inquiries, reporting issues, collection matters, and complex California tax controversies.
Her experience spans both proactive planning opportunities and high-consequence disputes involving the Internal Revenue Service, the California Franchise Tax Board, the California Department of Tax and Fee Administration, and the Employment Development Department.
Allen Barron also assists clients who are planning ahead, seeking to come into compliance, or addressing international tax concerns before they become larger disputes. Tax planning, voluntary compliance, offshore reporting, expatriate tax issues, international investments, and cross-border business activities often benefit from early, coordinated guidance. Taking the right steps now may help reduce exposure, preserve options, and prevent avoidable tax, legal, accounting, and financial consequences.
The initial consultation is a complimentary, substantive, confidential discussion designed to help you better understand your current position, the issues that may require immediate attention, and the strategies that may help protect your financial and business interests moving forward.
You are invited to engage the chat module on this page, contact Allen Barron, or call (866) 631-3470 to schedule a free, substantive consultation.
Learn more about Janathan L. Allen, APC and Allen Barron’s integrated tax, legal, accounting and business consulting services and how an integrated approach may help identify risk, protect assets, reduce unnecessary exposure, and support your long-term business and financial objectives.